See credit risk building in your loan book.
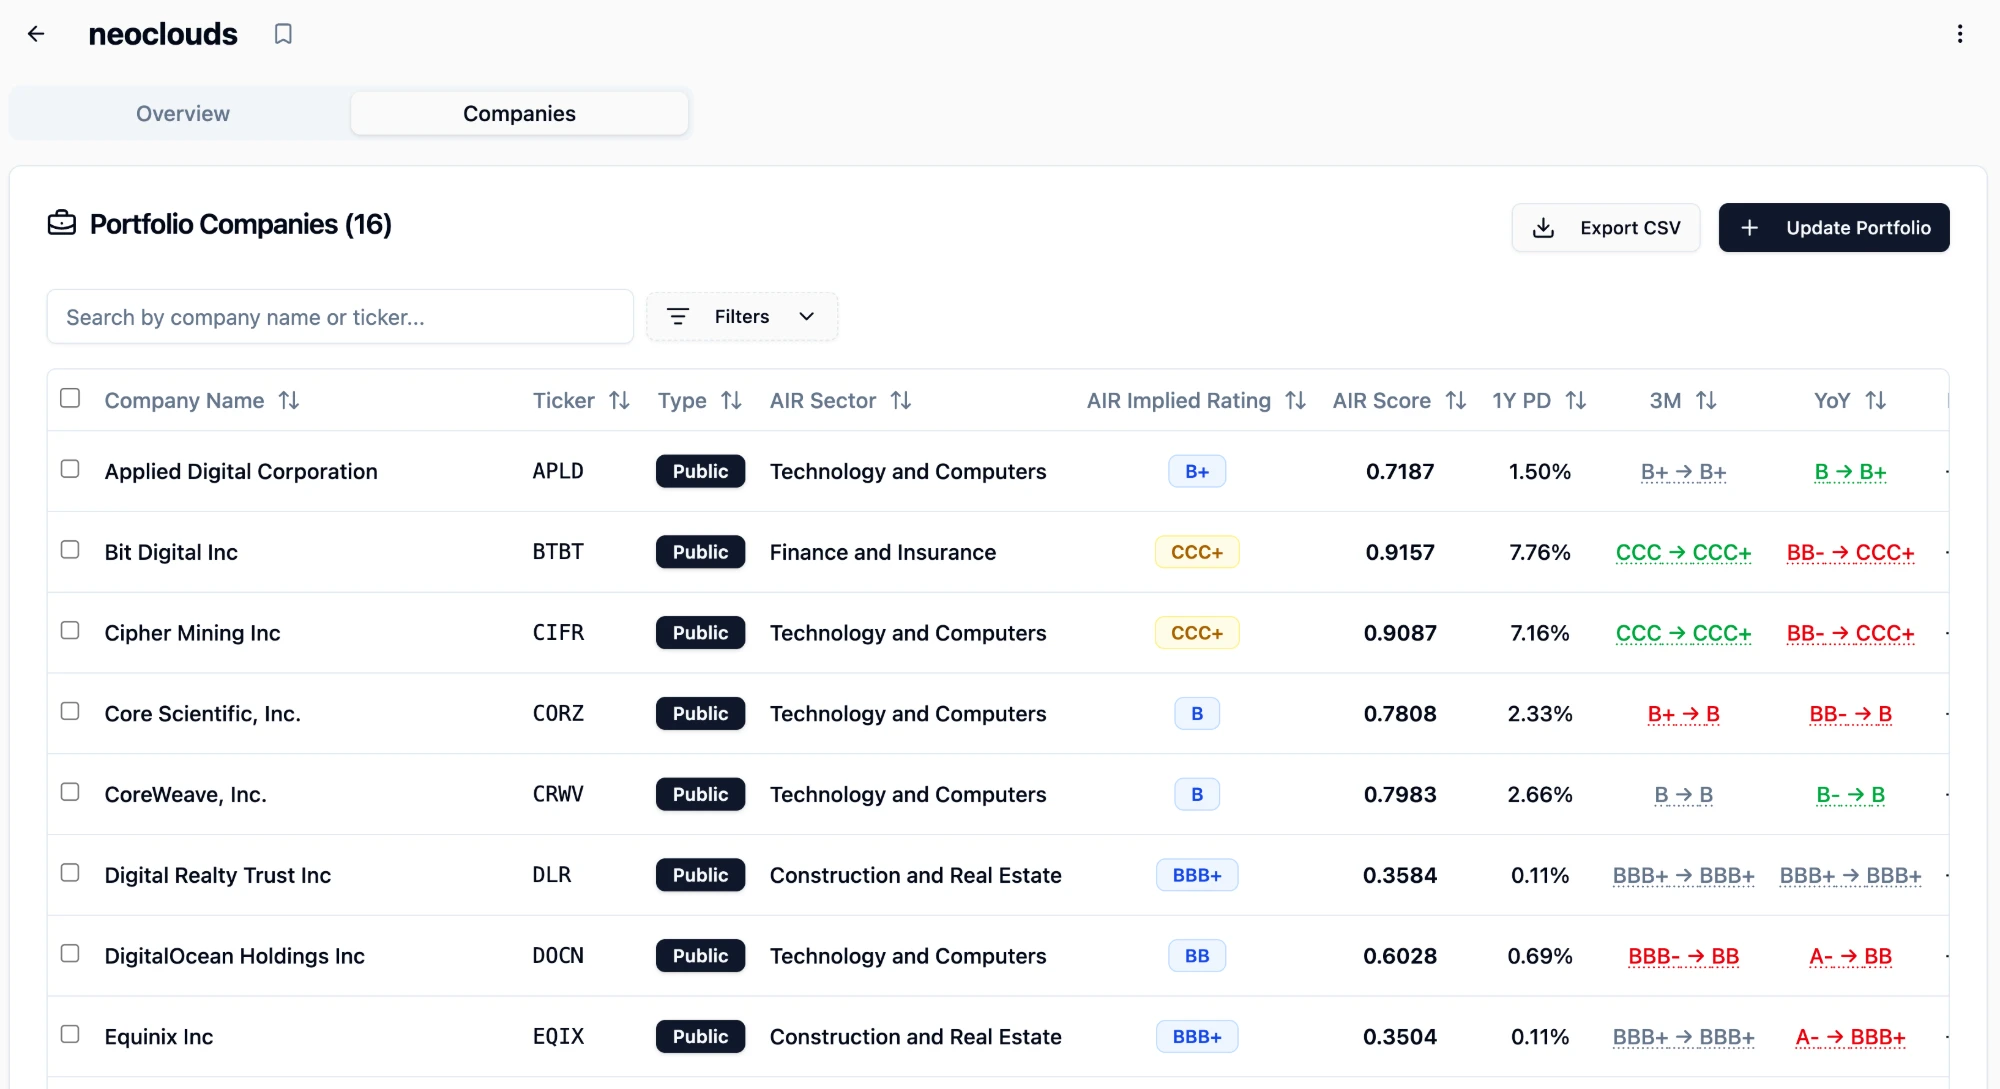
AIR assesses the private companies in your commercial and industrial (C&I) book, and flags deterioration between reviews, from origination for the life of the loan.
For credit, risk, and lending teams at global, regional & community banks, and credit unions.
Track record
- Lead on bond & loan price collapse
- 6mo
- Corporate debt scored daily
- $11T+
- A credit brain your bank owns
- Yours
Approve good loans sooner, and see trouble before it reaches your book.
Predictive.
Specialized models flag a private borrower’s deterioration before it happens, from the financials you already collect.
Work out a loan while there’s still time.
11–12 months earlierEarly credit deterioration · Global bankSystemic.
One scenario across your C&I book, showing where exposure concentrates.
Find concentrations before they become losses.
100% coverageBSL universe at scale · Asset manager · >$500B AUMFast.
From a private company’s financial statements to an assessment in minutes.
Say yes to good borrowers sooner.
10× fasterCredit decisions · Credit manager · ~$20B AUM
A commercial borrower starts to slip. Two ways it plays out.
The signal
Without AIR
You hear at the annual review, or when a covenant breaks.
With AIR
AIR flags it months earlier, between reviews.
The analysis
Without AIR
Statements spread by hand, then the memo. Days.
With AIR
Financials, drivers, peers, and AIR Implied Rating, ready. Minutes.
Your book
Without AIR
No one knows which loans share the same exposure.
With AIR
One scenario shows every borrower exposed to the same shock.
Different balance sheets. The same credit questions.
Global banks
AIR’s models alongside your own, across the private companies in large commercial portfolios.
Regional banks
One consistent view across a growing C&I book, from origination through monitoring.
Community banks & credit unions
Institutional-grade credit analysis for a lean team, across the local businesses you lend to.
Use AIR’s models, run your own, or build your credit brain with AIR.
- Models
Your models and AIR’s, side by side.
Use AIR’s models and features on your C&I book, or onboard your bank’s own models and run them alongside AIR’s, at origination and in ongoing monitoring.
- Credit brain
Your bank’s credit brain.
AIR’s team helps your bank build the foundation behind its own credit research and decisions: standardized data, curated context, and credit expertise built into the scaffolding your AI works within. It stays yours.
Underwrite with every number traced.
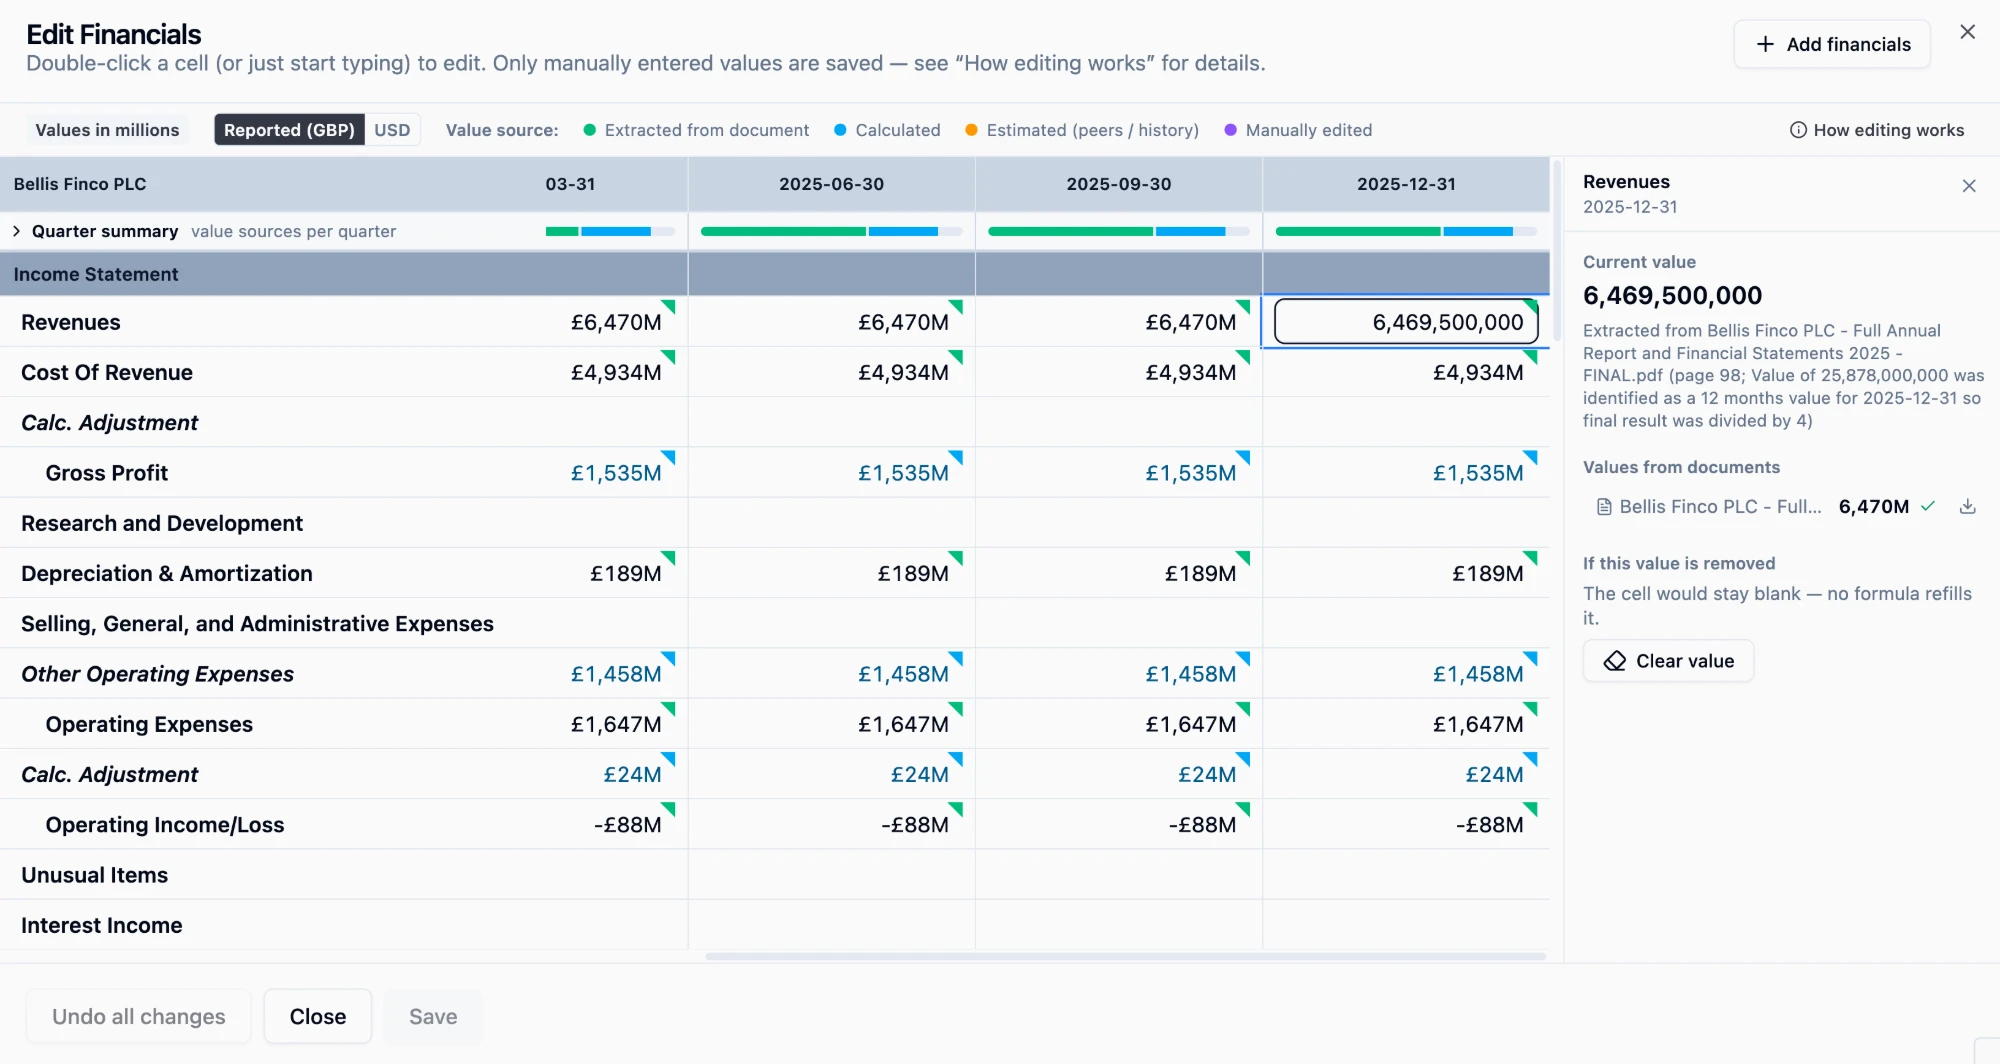
Assess a private borrower from the statements it provides, with each value traced to the page it came from. Let Financials Builder estimate anything missing, clearly labeled.
Catch deterioration between reviews.
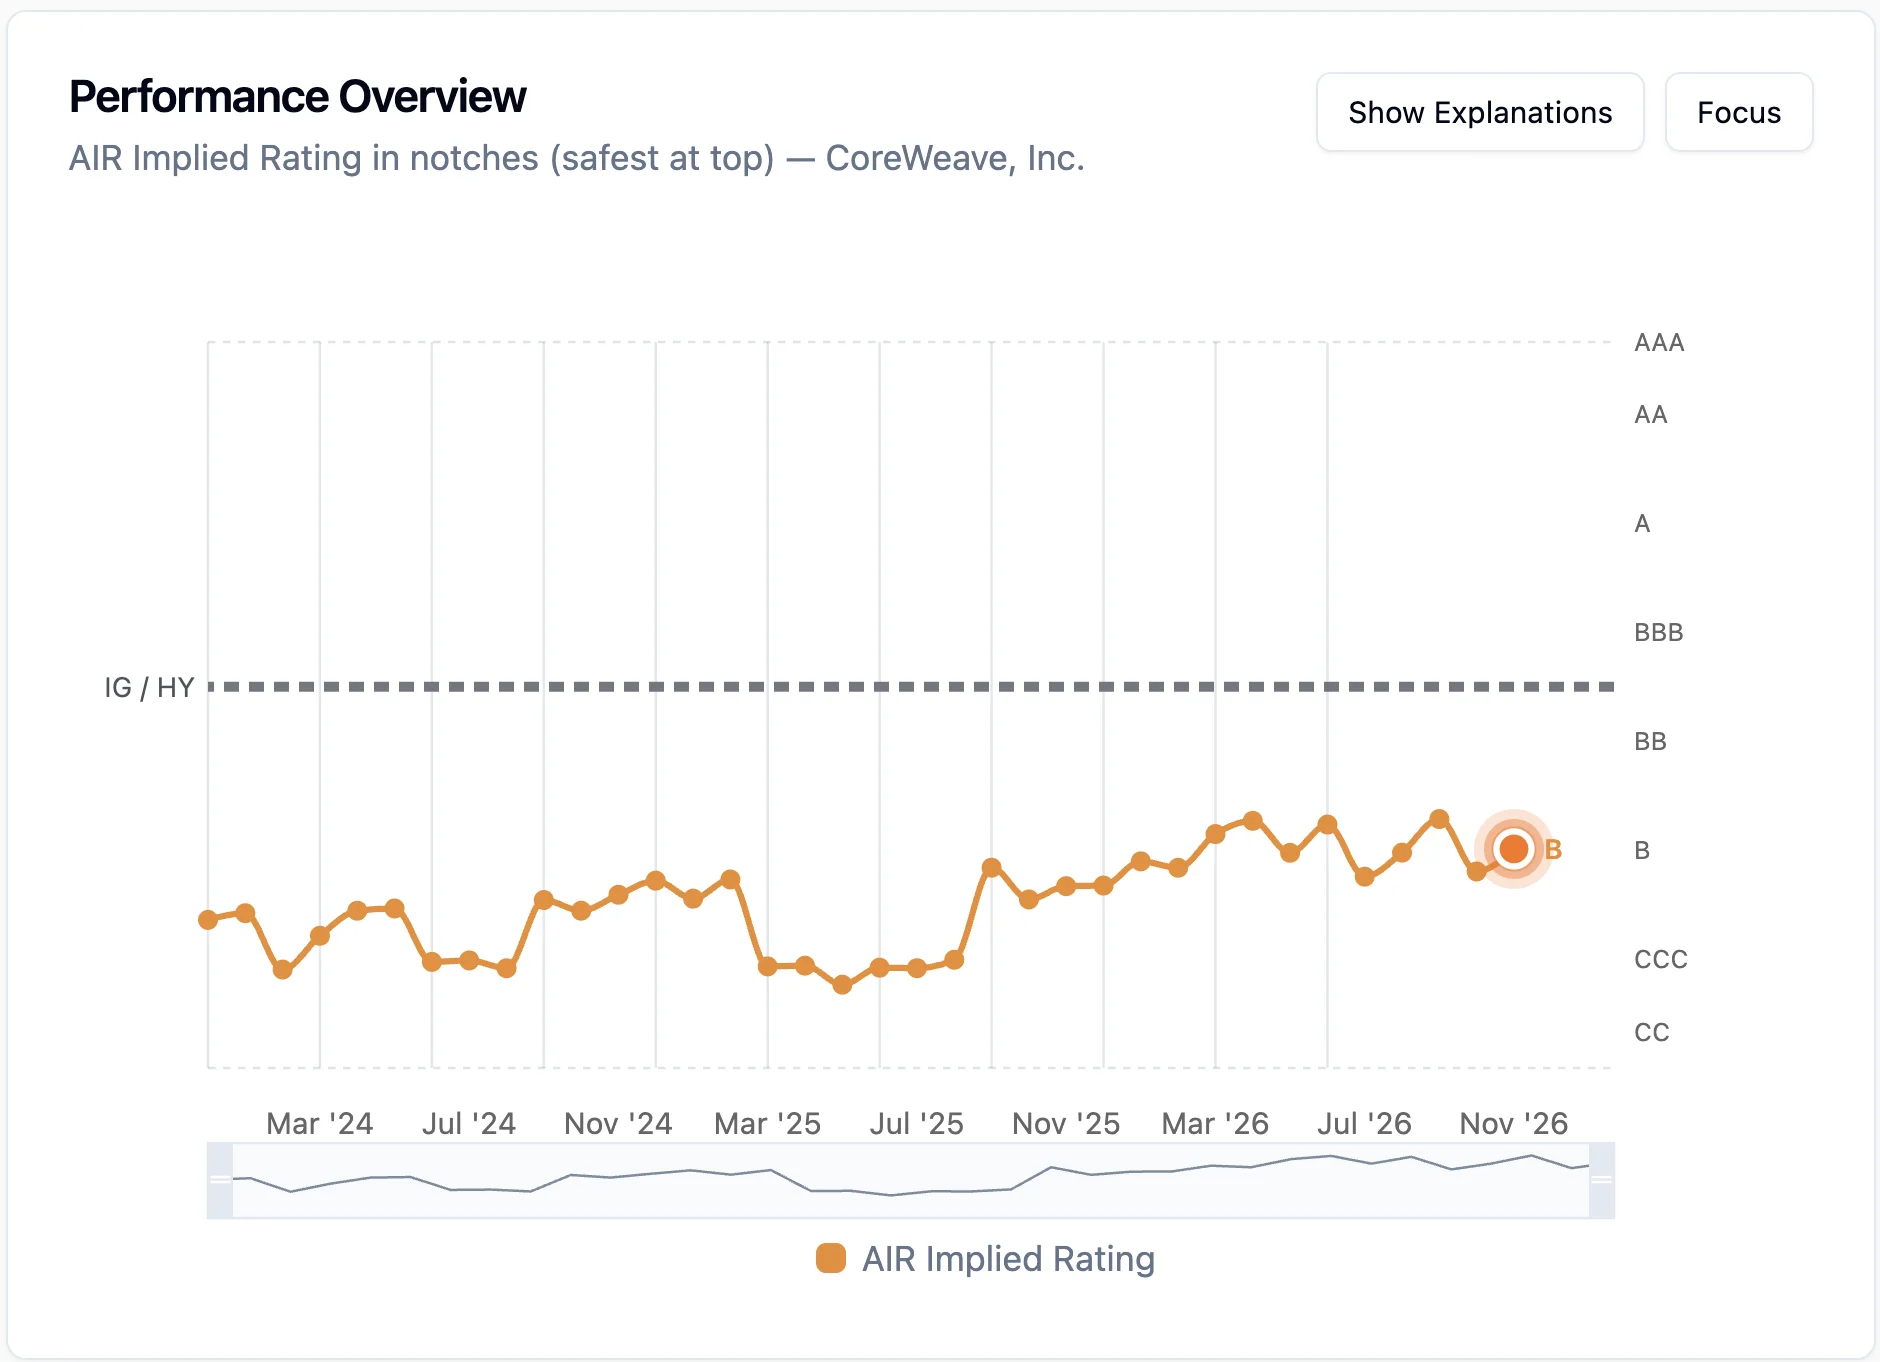
Daily credit signals and alerts, so your watch list reflects today, not the last annual review.
See which loans a shock would hit.
Describe a rate move, a sector downturn, or a regional slowdown, run it across your C&I book, and see where credit could change and why.
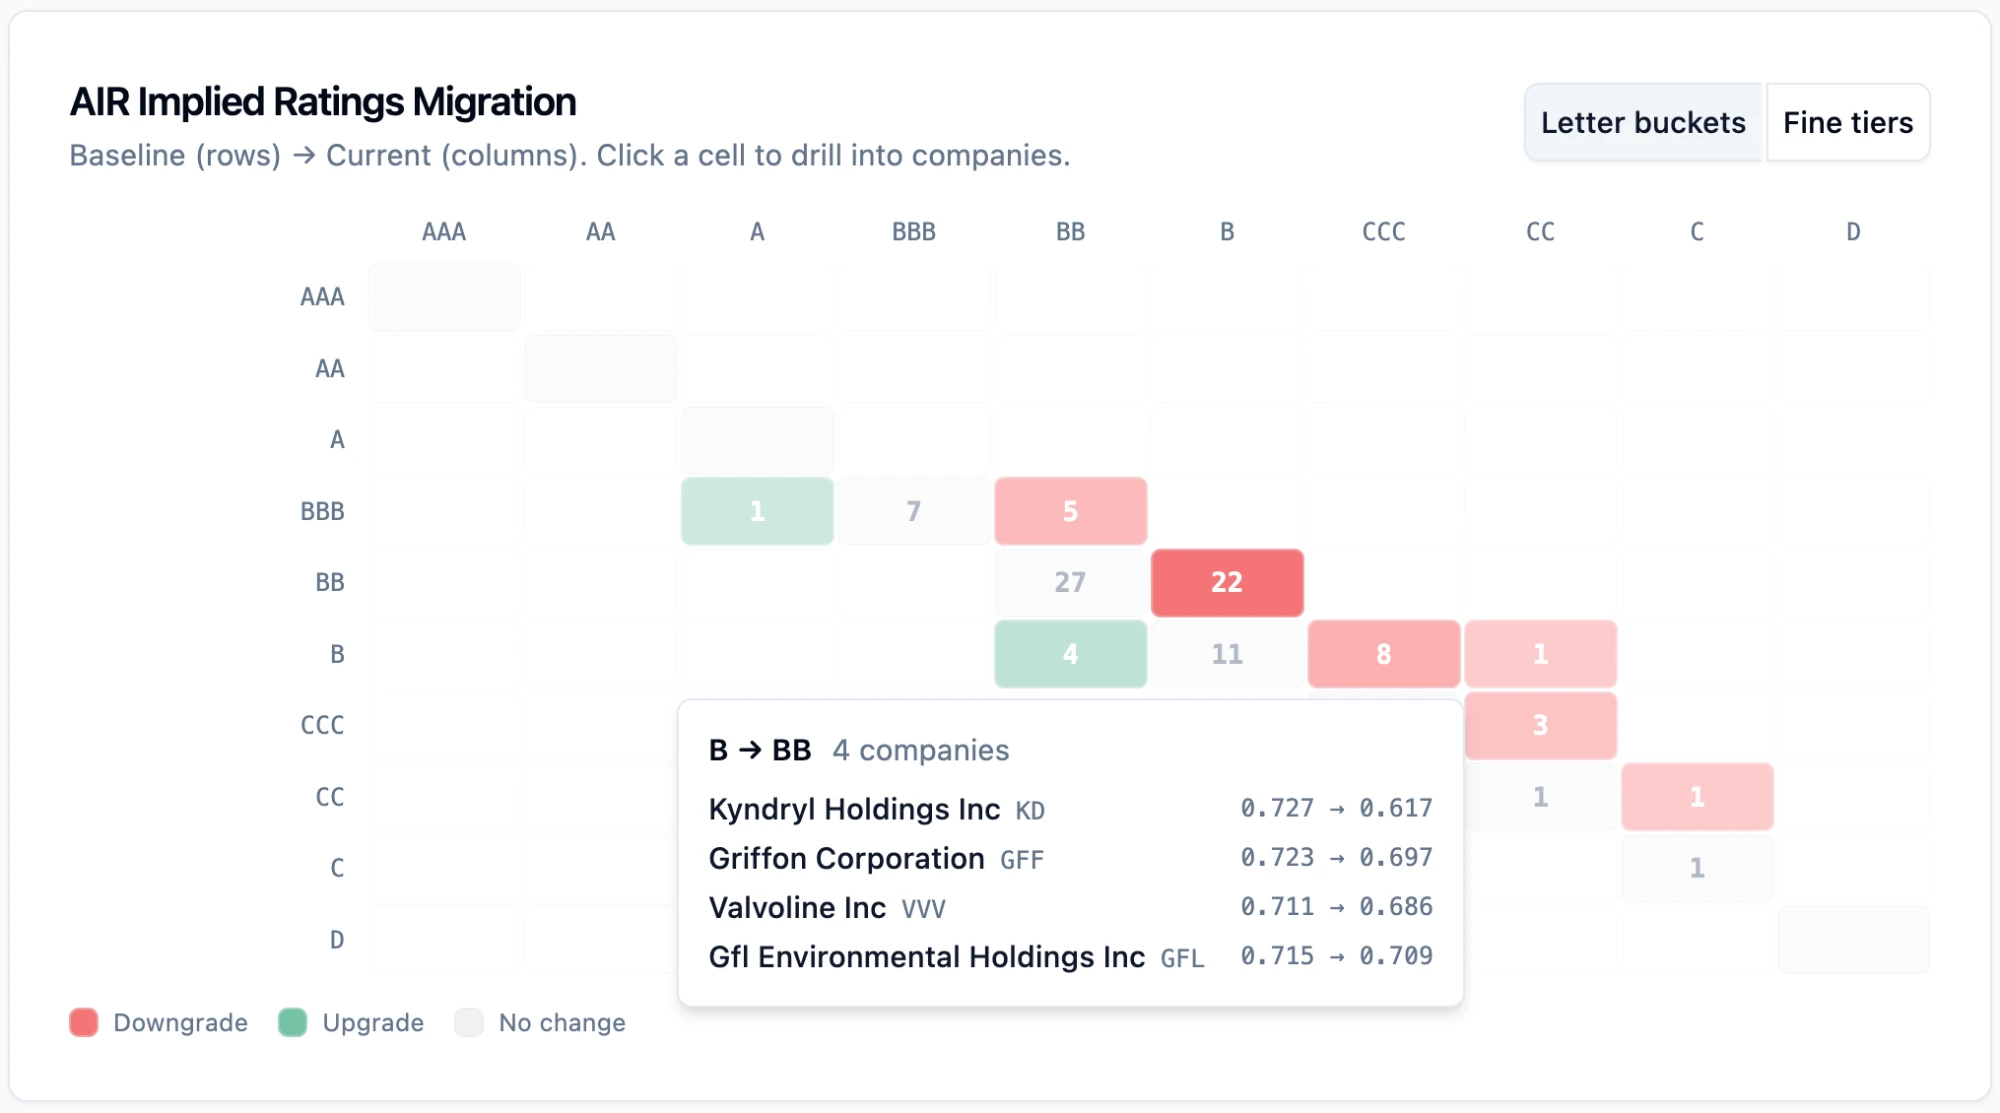
Built for model risk management.
Deterministic models produce the implied ratings, with the documentation your model risk team expects.
- Model cards for production models.
- Quarterly validation reports.
- Drift monitoring with alerting.
- Analyst override workflows with an audit trail.
Credit questions, worked through.
Analysis of real companies, from early warning signs to how a shock spreads.
- AIR Research · Credit deterioration
We're Back: The Children's Place Credit Unravels
Read analysison Substack (opens in a new tab) - AIR Research · Leverage and capital allocation
What’s FICO’s credit score?
Read analysison Substack (opens in a new tab) - AIR Research · Scenario analysis
A Different Credit Perspective on CoreWeave
Read analysison Substack (opens in a new tab)
What bank credit teams ask us.
Most of our borrowers are private companies. Can AIR assess them?
Yes. AIR is built for private companies. It assesses them from the financials you have, in PDF, Excel, or other formats, and Financials Builder estimates missing inputs. Extracted figures and estimates are clearly labeled, can be adjusted, and are fully traceable.
Can we run our own models in AIR?
Yes. Your bank can onboard its own credit models and run them alongside AIR’s, at origination and in ongoing monitoring, so you can compare results over time.
We already have AI initiatives. How does AIR fit in?
AIR works inside them. Your teams can use AIR in the assistants your bank already runs, such as Claude, ChatGPT, or Copilot, and through the API. AIR’s credit models produce the implied ratings; language models research and explain, but never make the credit call. Read why in Why LLMs Should Not Make Credit Decisions (opens Substack in a new tab). If your bank is building its own, AIR’s team can help engineer a credit brain: standardized data, curated context, and credit expertise built into the scaffolding your AI works within, owned by your bank.
How does AIR fit our model risk management?
AIR’s production models come with model cards, quarterly validation reports, drift monitoring, and override workflows with an audit trail. Documentation is available in the AIR Trust Center.
How does AIR compare with Moody’s EDF-X or S&P’s RiskGauge?
Both estimate company credit risk. AIR is built for how credit teams work now. Its specialized models flag deterioration early in private companies, and it adds scenarios across your whole book, your own models running alongside AIR’s, and AI agents in the workflow.
How does AIR protect our data?
AIR is SOC 2 Type II. Customer data is segregated by tenant and is not used to train AIR’s models. Single-tenant deployment is available. Trust & Security.
See your borrowers in AIR Intelligence.
Share a few borrowers from your book, and AIR's team will walk you through their assessments, credit drivers, and scenarios.